November is benefits month across the South Bay. Covered California opened enrollment for 2027 on November 1, and plenty of Santa Clara County employers are running their own sign up windows for plans that start January 1. Medical plans get most of the attention, which makes sense. But the open enrollment life insurance choices usually sit a couple of screens later, and they are the ones most often clicked past without a second look. Here is what we think is worth checking before the window closes.
Work Coverage Is Common. Relying on It Alone Is the Gap.
LIMRA’s 2026 workplace benefits fact sheet says 47 percent of insured Americans have life insurance through their job, and 27 percent have workplace coverage with no individual policy at all. That second group is the one we worry about. Their coverage is tied to a paycheck, and it usually ends when the job does.
The bigger picture from the 2026 LIMRA and Life Happens research is not much better. Only 52 percent of adults own any life insurance, about 92 million say they need it or need more, and just 29 percent believe their household would stay financially secure for more than two years after losing a primary earner. We dug into the workplace side of this back in October in Is Workplace Life Insurance Enough in the Bay Area?
Open Enrollment Life Insurance Choices, Line by Line
Basic life. This is the coverage an employer pays for. It is usually a flat amount or a multiple of salary, and it is a nice benefit. It is also rarely sized for a Bay Area mortgage and a couple of kids.
Supplemental life. This is extra coverage paid through payroll deductions, often with options for a spouse and children. Larger elections can come with health questions, and the plan documents spell out when. Supplemental coverage can be a handy add on, but it carries the same weakness as basic life: it lives inside the job.
The tax line on the paystub. According to the IRS, employer provided group term life coverage up to $50,000 has no tax consequences. The cost of coverage above that amount counts as taxable income, figured from an IRS premium table, and it is subject to Social Security and Medicare taxes. That small “imputed income” line confuses a lot of people every January. It is not a reason to turn coverage down, just something to understand.
Changing Jobs? The 31 Day Clock
Job changes are a fact of life in Silicon Valley, and 2026 has been a busy year for them. WARN filings tallied by Hidden Jobs show about 13,900 Bay Area tech positions cut through September, 36.6 percent more than in all of 2025, including 251 at PayPal’s San Jose headquarters.
When work coverage ends, there are usually two ways to keep some of it. MetLife’s explainer lays out the difference: portability keeps term coverage with rates based on age at the time and subject to change, while conversion turns it into permanent whole life with no medical questions and a fixed rate. Both generally have to be requested within 31 days of benefits ending. Miss that window and the option is usually gone. Whole life costs more than term for the same death benefit, which we explain in Term Life vs. Whole Life: A Practical Comparison.
A Morgan Hill Reality Check
The U.S. Census Bureau puts Morgan Hill’s median household income at $159,758 (2019 to 2023, in 2023 dollars). Picture a plan that pays one year of salary. For a household near that median, that is roughly one year of breathing room, when a mortgage on a home off Monterey Road and kids at Live Oak or Sobrato High can stretch 15 or 20 years. Our guide How Much Life Insurance Is Really Needed? walks through a fuller way to add it up.
Then there are the people with no employer enrollment at all: the shop owners on Third Street, contractors, and freelancers. Covered California enrollment runs through January 31, 2027, with a December 31 deadline to have health coverage start January 1. That handles medical. Life insurance is a separate step, and for most self employed families an individual term policy is the piece to add.
Five Questions to Answer Before Clicking Submit
- What does the basic plan actually pay? Find the number in the benefits portal, not the brochure summary.
- Is supplemental the best place for extra coverage? Compare the payroll cost with an individual level term policy, which keeps the same price for the length of the term and stays in place after a job change.
- Are the beneficiaries current? Marriages, divorces and new babies all call for an update. The NAIC beneficiary guide covers the basics, including why naming a minor child directly causes problems.
- Does the family know where the paperwork is? In an Aflac survey released October 6, 38 percent of workers who had written down their wishes did not think loved ones knew where to find them. Billions in benefits go unclaimed for this reason, as we covered in Nearly $17 Billion in Lost Life Insurance Found.
- Is there a person to call? An HR portal will not sit down with a family after a loss. A local agent costs the same as buying online, and the policy can come from a strong, long standing carrier. More on why that matters in Who’s Your Agent? Trust in Life Insurers Fell in 2026.
Common Questions
Is life insurance through work enough on its own? For most South Bay families, probably not. Work coverage is often a flat amount or one or two times salary, and it usually ends with the job. Many people keep the work benefit and add an individual term policy that stays put.
Does work life insurance follow an employee to a new job? Not automatically. Many group plans offer portability or conversion, but the request generally has to be made within 31 days after coverage ends, and the price is based on age at that point.
Is employer life insurance over $50,000 taxable? The IRS treats the cost of employer provided group term coverage above $50,000 as taxable income, which shows up on the paystub and the year end tax form. Coverage at or below $50,000 has no tax consequences.
Helpful Resources for California Families
- California Department of Insurance: Life Insurance and Annuities, consumer guides from the state regulator.
- Life Happens needs calculator, a free nonprofit tool for estimating coverage.
- LIMRA Insurance Barometer Study, annual research on how Americans buy and view life insurance.
- NAIC guide to beneficiaries, from the national association of state insurance regulators.
- IRS: Group Term Life Insurance, the $50,000 rule explained.
- Covered California, health plan enrollment for the self employed and anyone without job based coverage.
The Bottom Line
Open enrollment is a good yearly reminder to look at the whole plan, not just the medical tab. Take the free coverage at work, understand what it pays and when it ends, and make sure the family has something that does not depend on one employer. A strong carrier matters too, as we explain in Why the Industry Giants Are the Safer Choice.
So, who’s your agent? If you don’t have one, we’d be happy to help. Families in Morgan Hill, Gilroy, San Jose and across the South Bay can learn more about us, get in touch or request a quote, with no pressure.
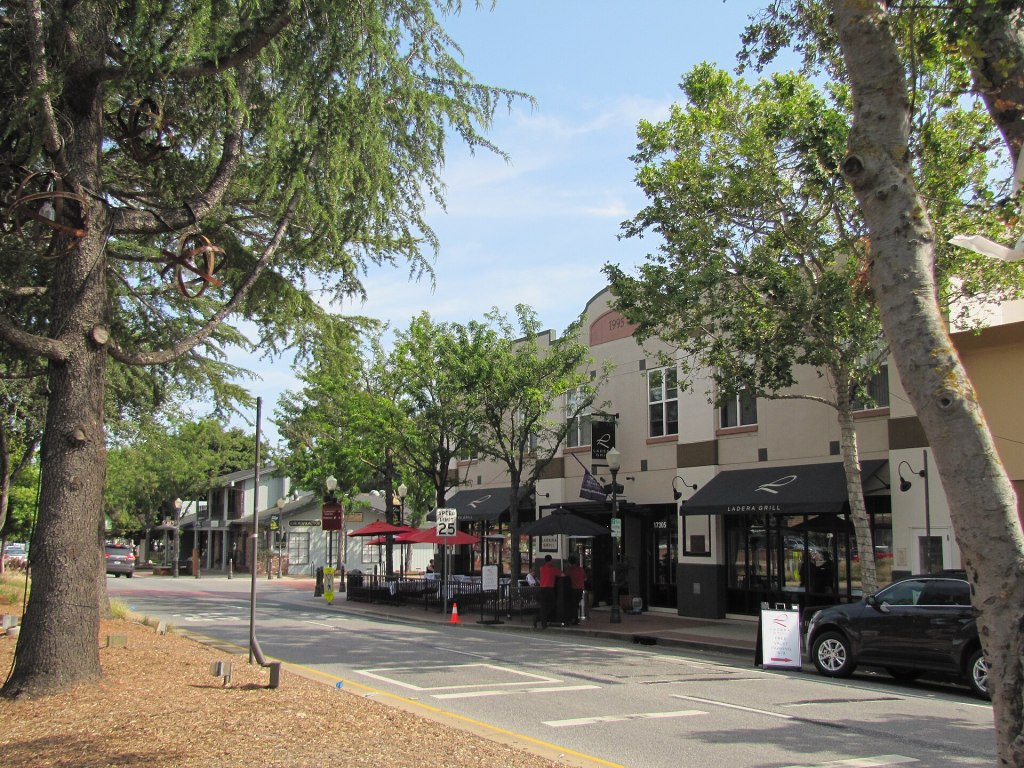
Sources: LIMRA 2026 Facts About Life Insurance and workplace benefits fact sheets; LIMRA and Life Happens 2026 Insurance Barometer Study; IRS, Group Term Life Insurance; MetLife, portability and conversion overview; Hidden Jobs (September 24, 2026), based on WARN filings; U.S. Census Bureau QuickFacts, Morgan Hill; Covered California (October 30, 2026); Aflac Life Insurance and Legacy Planning Study (October 6, 2026); NAIC Consumer Insight on beneficiaries. Photo: Downtown Morgan Hill (3rd and Monterey) by Cristiano Tomás, CC BY SA 4.0, via Wikimedia Commons. This post is for general education and is not personalized financial advice.


Leave a Reply